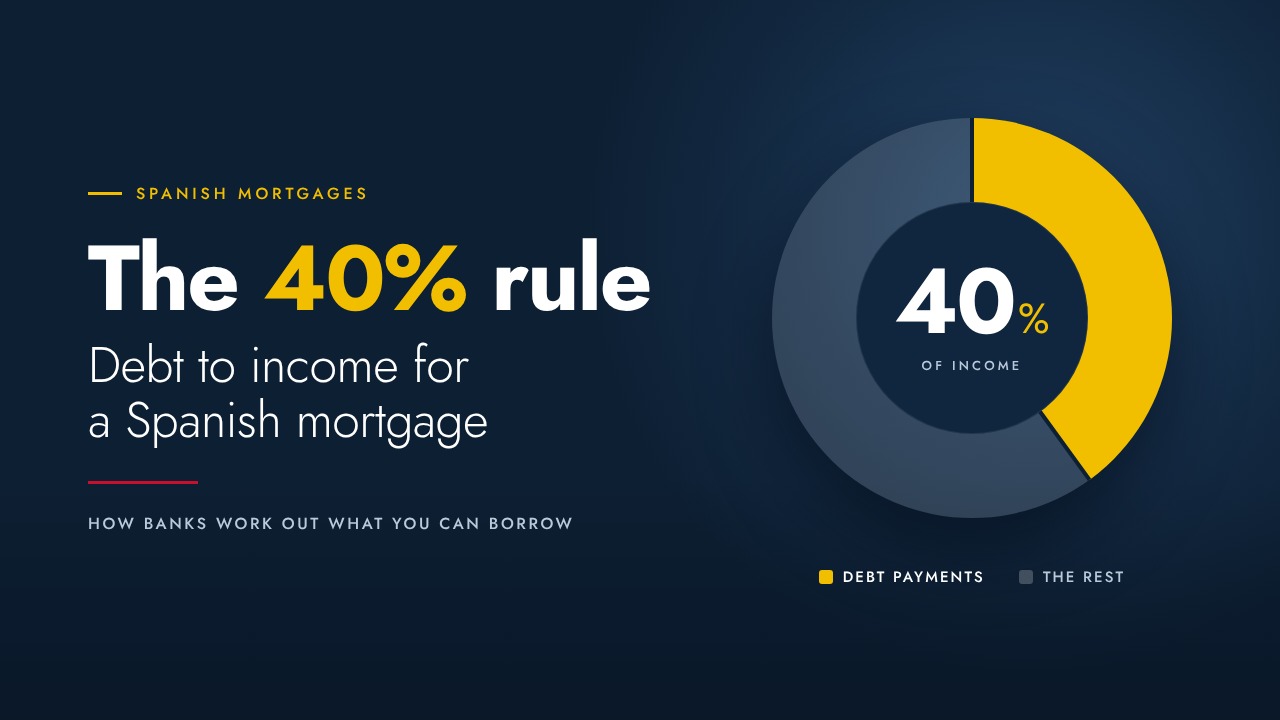

The amount a Spanish bank will lend you is set by one calculation. Your monthly debt payments, including the new Spanish mortgage, can come to no more than 40% of what you take home each month. Banks call this your debt to income ratio.
If you take home 5,000 euros a month, your existing debts and the new mortgage together can cost up to 2,000 euros a month.
This is different from the UK and the US, where lenders start from a multiple of your salary. In Spain, a car loan or a credit card balance at home can reduce what you are offered, even on a high salary. This page explains how the calculation works, what counts as debt, and what to do if you are over the limit.
How the ratio is worked out
The bank adds up every debt payment you make each month, adds the payment on the new mortgage, and divides the total by your monthly income after tax. To see what you can afford, work it the other way.
Take your net monthly income
The amount that reaches your bank account after tax and deductions.
Multiply it by 0.4
That is the most all your debt payments can come to each month.
Subtract the debt payments you already make
What is left is the most the new mortgage payment can be.
| Example | You take home 5,000 euros a month |
|---|---|
| Mortgage at home, 1,300 euros a month | Uses 26% of your income |
| Room left under the 40% limit | 14% |
| New Spanish mortgage payment | About 700 euros a month |
Why this is different from the UK or the US
Lenders in the UK and the US often start from a multiple of your gross annual salary. Spanish banks do not use salary multiples. They work from what reaches your bank account each month and what leaves it in debt payments. Two people on the same salary can be offered very different mortgages in Spain, because one has a car loan and the other does not.
What counts as debt
| Counted | How the bank counts it |
|---|---|
| A mortgage you already have | The full monthly payment, even if the mortgage is in joint names |
| Car finance and personal loans | The monthly payment |
| Credit cards | The minimum monthly payment on your credit report, not the balance |
| Child support | The monthly amount |
| Rent | Counted if the Spanish property is a second home, or you will keep renting elsewhere. Not counted if you are buying your main home in Spain and moving into it |
| Debts in another country | All of them, converted to euros. The bank sees them on your credit reports |
Rent is counted as a monthly cost even if you pay it once a year.
What counts as income
The bank uses your net monthly income, the amount that arrives in your account after tax and deductions.
The limit: 40%, or below 35%
| Your situation | Limit |
|---|---|
| You earn in euros, wherever you live | 40% |
| You live outside Spain and earn in another currency, such as pounds or dollars | Below 35% at the more cautious banks |
The lower limit allows for movement in the exchange rate between your income and a mortgage paid in euros. Every bank sets its own rules, so treat these figures as a guide and not an offer. For how much you can borrow and the deposit you need when you live abroad, see Spanish mortgages for non-residents.
What to do if your ratio is too high
Reduce the debts with the largest monthly payments
The ratio is monthly, so a car loan costing 900 euros a month matters far more than a larger debt with a small payment. Say you take home 4,800 euros a month and pay 900 euros on a car loan and 300 euros on other debts. That is 25% before any mortgage. Clear the car loan and it falls to 6%.
A part reduction can be enough
Halving a car payment, or refinancing a loan over a longer term, lowers the monthly figure the bank counts. You do not always need to clear a debt completely.
Clear credit card balances before you apply
The bank counts the minimum payment on every card, so cards with balances reduce what you can borrow.
Look at who is on the application
Adding a partner brings in their income and their debts. Someone with a good income and little debt improves the ratio. Someone with a low income and several debts can push it over the limit.
If it will be your main home, say so
When you are moving to Spain and will live in the property, your current rent is left out of the calculation.
Two things that help less than people expect
A bigger deposit. It lowers the new mortgage payment only slightly, so the ratio barely moves. See how much deposit you need.
A cheaper property. Dropping from a 220,000 euro property to a 180,000 euro one improves the ratio by about two percentage points. If you are well over the limit, that will not be enough on its own.
See your own ratio in about a minute
The mortgage score tool works out your debt to income ratio from your income and your monthly debts, and shows the deposit and buying costs for the region you are buying in.
Common questions
Is the 40% worked out on gross or net income?
Net. The bank uses your monthly income after tax, the amount paid into your account.
Does my mortgage at home count if it is in joint names?
Yes. The bank counts the full monthly payment against you, even if someone else pays half.
Do my savings help?
Not with the amount you can borrow. Savings make you a stronger applicant once you qualify on income and debts, but the ratio is what sets the mortgage.
I am over the limit by a few points. Is that the end of it?
No. Paying down or restructuring one debt with a high monthly payment is often enough. Speak to us before you apply and we will work through which debt to deal with first.
Foxes is a credit intermediary registered with the Bank of Spain (D470), not a lender. The figures here are a guide. The bank sets the terms after a full assessment.